For many professionals, the path to financial independence begins with a simple question:
✈️ How can I make my money work without creating another full-time job? 💰
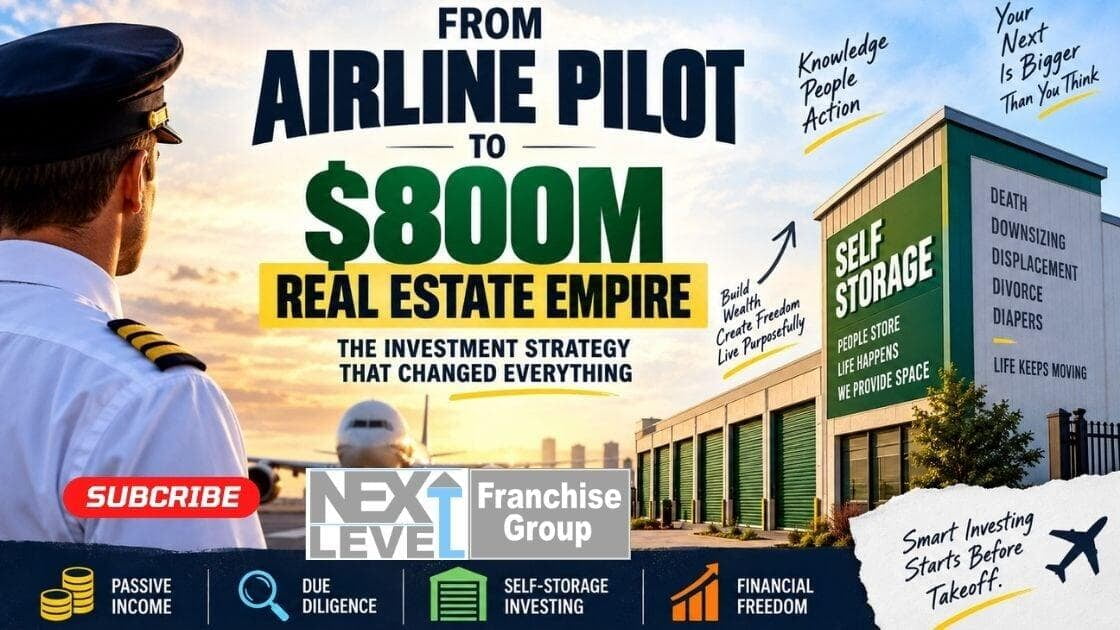
That question sits at the heart of Ryan Gibson’s journey from commercial airline pilot to co-founder of Spartan Investment Group. His experience with real estate investing, particularly self-storage, offers a broader lesson about building wealth: attractive returns matter, but understanding risk, people, operations, and leverage matters even more.
🏠 From Passive Income to a Second Job
Gibson initially turned to single-family rental properties in search of passive income. On paper, rental real estate appeared to provide exactly what he wanted: recurring cash flow combined with long-term asset ownership.
The reality was different.
Managing individual properties introduced many of the responsibilities associated with running a business. Tenants, maintenance, repairs, vacancies, financing, and property management all required attention.
This distinction matters because investors sometimes confuse owning an investment with having a passive investment.
A property may produce income, but if the owner must continually operate it, that income isn't necessarily passive.
Gibson eventually gravitated toward real-estate syndications and larger-scale investing, where investors can provide capital while professional operators handle acquisitions and ongoing management.
His organization subsequently grew to more than $500 million in equity raised and $800 million in assets under management, illustrating how dramatically the model can scale. 📈
✈️ Invest Like an Airline Pilot
One of Gibson's most useful concepts comes directly from aviation.
Commercial pilots don't simply arrive at an airplane and take off. They use procedures, checklists, inspections, weather information, operational data, and multiple layers of risk management before committing to a flight.
Investors can approach opportunities the same way.
The best time to discover a problem isn't after purchasing an asset. It's before the money is committed.
Gibson compares this concept with aviation's V1 decision speed. Before that critical point during takeoff, a pilot may still be able to safely reject the takeoff. After passing it, continuing generally becomes the appropriate course of action.
An investment has a similar boundary.
Before signing and funding, you can investigate, challenge assumptions, renegotiate, or walk away. Once the transaction closes, fixing a mistake can become much more expensive.
That makes due diligence one of an investor's most powerful forms of risk management. 🔎
🧠 Knowledge → People → Action
Gibson presents a straightforward framework for moving into a new investment category:
Knowledge → People → Action
First comes knowledge.
An investor doesn't need to become an expert in every technical aspect of self-storage, commercial real estate, financing, or property management. But investors should understand enough to recognize questionable assumptions and ask intelligent questions.
Blind delegation is dangerous.
Next come people.
Once you understand the fundamentals, identify people with genuine experience. That can include operators, investors, advisers, lenders, brokers, accountants, attorneys, and experienced peers.
But evaluating those people requires more than examining successful deals.
One particularly valuable suggestion from Gibson is to ask an investment operator about their worst-performing investment.
Then ask to speak with someone who invested in it.
A successful project can conceal weaknesses because favorable market conditions sometimes compensate for mistakes. A difficult project reveals how an operator communicates, solves problems, protects investors, and responds when assumptions fail.
Finally comes action.
Education can become its own form of procrastination. Eventually, investors must move from reading and researching to making carefully considered decisions.
🏢 Why Self-Storage Is an Interesting Business
Self-storage can appear deceptively simple.
Someone owns a building containing many small units. Customers rent those units. Money arrives every month.
But Gibson argues that operating self-storage investing assets isn't truly passive for the operator.
Facilities require marketing, customer acquisition, maintenance, staffing, capital expenditures, revenue management, insurance administration, and numerous other operating functions.
Demand also has distinctive characteristics.
Gibson describes many customers as being driven by the five Ds:
Death, downsizing, displacement, divorce, and diapers.
These represent major life transitions that can suddenly create a need for additional space.
Businesses are another meaningful customer group. Contractors, sales representatives, small businesses, and other organizations may use storage units as flexible and comparatively inexpensive operating space.
Approximately 70% of customers, according to figures discussed in the conversation, are associated with life-event demand, while around 30% are business customers.
📍 Self-Storage Is an Intensely Local Business
A common mistake is looking at a city filled with storage facilities and concluding that the market must be saturated.
Gibson argues that the analysis needs to be much more localized.
A facility's real competitive environment may exist within only a three-to-five-mile radius.
Two facilities in the same metropolitan area can therefore have dramatically different economics.
Population growth, household income, housing characteristics, renter concentration, competing supply, occupancy rates, rental rates, and construction pipelines all matter.
National statistics provide context, but they don't answer the fundamental question:
Is this particular property attractive in this particular location at this particular price?
That distinction applies well beyond storage. Investors should avoid allowing compelling macroeconomic narratives to substitute for asset-level analysis.
👨👩👧 Demographics Can Create Long-Term Demand
Storage demand also reflects demographic and lifestyle changes.
Older Americans may accumulate possessions over decades and eventually inherit additional belongings from relatives. Downsizing can create another storage requirement.
Younger generations can generate demand differently. People living in smaller homes or apartments may own recreational equipment—bicycles, skis, paddleboards, motorcycles, camping equipment, and other items—that they cannot conveniently keep at home.
Housing affordability also plays a role.
People who rent tend to move more frequently than homeowners. Moving itself is one of the circumstances that can trigger storage demand.
Gibson points to a striking long-term trend: storage usage in the United States has increased from roughly two square feet per person to more than seven square feet per person.
Industry occupancy, according to the figures discussed, has also risen from approximately 70% around four decades ago to roughly 90.5% today, despite considerable new construction.
Those numbers don't guarantee future performance, but they help explain why institutional investors have become interested in the category.
💵 The Hidden Power of Net Operating Income
One of the most valuable commercial-real-estate lessons from the discussion concerns net operating income (NOI).
Commercial property values are closely connected to the income those properties generate.
That means operators aren't limited to waiting for surrounding real-estate prices to increase. Improving operations can potentially increase the property's value.
Suppose a facility generates additional recurring revenue without creating an equivalent increase in expenses. That can increase NOI.
Tenant insurance provides one example discussed by Gibson.
If properly structured, insurance-related revenue can add to facility economics. Increased NOI can subsequently translate into increased asset value.
This illustrates an important distinction between commercial real estate and many residential investments:
Operational skill can create equity. 🚀
⚠️ Why ROI Can Be Misleading
Perhaps the most important lesson in the conversation is Gibson's warning about focusing too quickly on projected returns.
Imagine two investments.
One advertises a 15% return.
Another advertises 20%.
The second investment may appear obviously superior.
But that conclusion is impossible without knowing how those returns are being produced.
Leverage is a major reason.
Debt can amplify returns on investor equity. If an asset performs well, borrowing money can make the equity investor's percentage return substantially higher.
But leverage works in both directions.
If the asset performs poorly, debt can magnify losses as well.
Therefore, comparing projected returns without comparing leverage, loan terms, interest-rate exposure, operating assumptions, and downside scenarios can create a false impression of investment quality.
Instead of beginning with:
“What's the ROI?”
Investors should first ask:
How much debt is being used?
What are the loan terms?
Is the interest rate fixed or floating?
What assumptions drive revenue growth?
What happens if occupancy declines?
How much cash reserve exists?
What is the operator's track record?
What happened during the operator's worst deal?
How are investor and operator incentives aligned?
Only after understanding those factors does the projected return become meaningful.
👥 Find Rooms Where You're Not the Expert
For professionals approaching their 40s and beyond, Gibson offers another practical lesson: deliberately seek environments containing people who know more than you do.
His advice can be summarized as becoming the “dumbest person in the room.”
The idea isn't to undervalue your own knowledge. It's to increase the quality of the information surrounding you.
Someone earning a good W-2 income may have developed tremendous expertise in medicine, engineering, aviation, law, technology, management, or another profession while knowing comparatively little about alternative investments.
Entering sophisticated investor communities can accelerate that learning.
But Gibson's framework remains the same:
Learn. Find good people. Take informed action. 🎯
🛫 Build Your Financial Flight Plan
Gibson's broader philosophy is captured by the aviation metaphor behind his upcoming book, The Financial Flight Plan.
Financial independence isn't simply about finding an investment promising the highest return.
It's about designing a process.
Know where you're trying to go. Understand the vehicle you're using to get there. Identify risks before committing capital. Surround yourself with competent people. Develop checklists. Learn from previous decisions. And don't allow attractive numbers to distract you from understanding what produces them.
The strongest lesson from Gibson's experience may therefore be surprisingly simple:
Good investing isn't primarily about predicting what will go right. It's about understanding what could go wrong before you commit—and deciding whether the potential reward adequately compensates you for that risk.
What's Your Next? - Podcast
 | Author BioI’m Stacey Riska aka “Small Business Stacey”, your franchise placement specialist. I help aspiring business owners find the PERFECT franchise so they can get to the next level in life and business. |